October 22, 2026
You Missed the SAVE Deadline
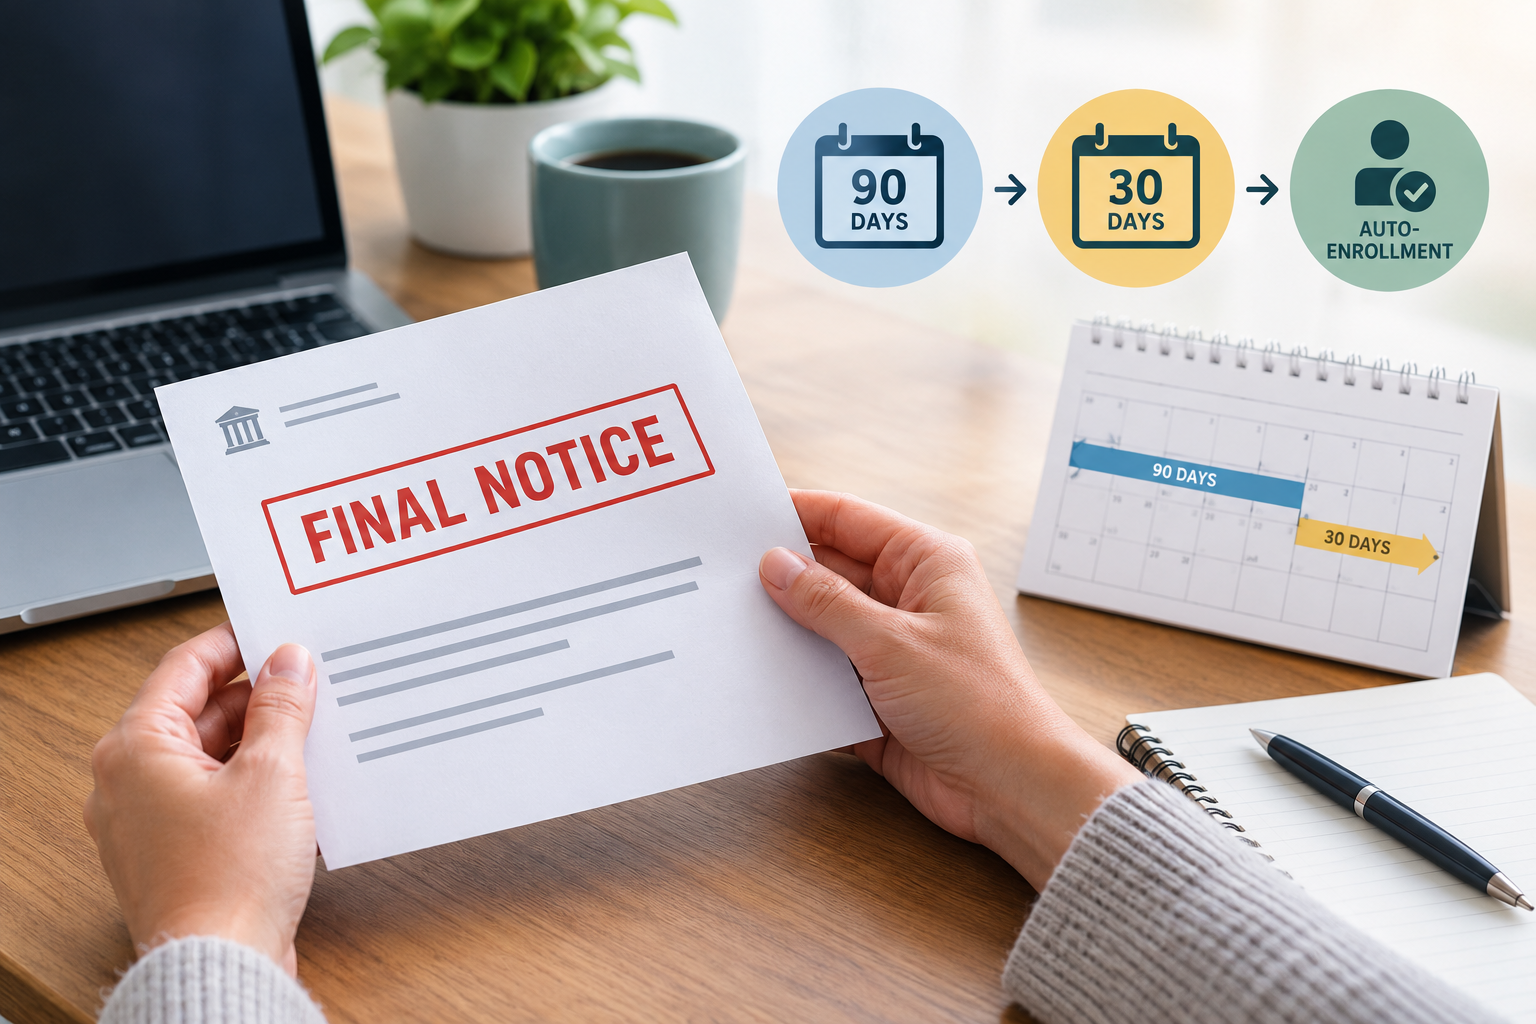
The letters started going out in October and the subject line is doing a lot of work: “Final Notice – You will be Placed into a New Repayment Plan in 30 Days.”
If one of those landed in your inbox, the first useful thing to know is that it isn’t a penalty notice and nothing has been taken away from you. It’s the second step in a process that has a third step, and you’re still inside it.
Here’s the actual sequence.
The 90 days, then 30 more
When SAVE was terminated, the Department set up a rolling transition. Each borrower’s servicer sends a notice, and from the date on that notice the borrower has 90 days to choose a new repayment plan. A great many people did not choose. More than a million borrowers have moved to a new plan; as many as six million either haven’t applied or have an application sitting in a queue somewhere. What happens when the 90 days expire is the part most coverage skipped: you are not enrolled in anything automatically at that point. Instead, your servicer sends a final notice giving you another 30 days. Only after that second window closes does auto-enrollment happen. So a frightening letter in late October generally means a real decision window that runs into late November.Where you land if you don’t choose
This is determined by your loans, not by your preference. If you have no loans first disbursed on or after July 1, 2026, you’re placed in the Standard Repayment Plan. If you do have a loan disbursed on or after July 1, 2026 that has entered repayment, you’re placed in the Tiered Standard Plan. This is important because Standard Repayment plans typically do not count toward forgiveness programs. Someone ten years into a public service career who gets dropped onto a Standard Plan and doesn’t notice could be making payments that build toward nothing. Neither plan is calculated from your income. For borrowers who had a low or zero payment under SAVE, the jump can be substantial.Two details that work in your favor
You get 21 days’ notice of the new amount. Servicers are required to tell you what your new payment will be at least 21 days before the first one is due. Nobody should find out by way of an unexpected withdrawal. Nothing here is permanent. Being auto-enrolled in a plan is not a trap. A borrower can apply to change plans afterward. It’s worse than choosing deliberately — you may make payments at the wrong amount in the meantime, and if you’re on a forgiveness track you may lose months that would otherwise have counted — but it is recoverable.Two details that don’t
Some deadlines have quietly moved, with no announcement. Individual borrowers have had their dates pushed two to four weeks later without explanation or any update to the Department’s published guidance. That cuts both ways: the date in your head may not be the date in the system, and the only reliable source is the notice you actually received. Pending SAVE applications are being denied. If you applied for SAVE and have been waiting, that application isn’t a placeholder. Borrowers who ignore both notices revert to whatever plan they were on before SAVE.What the right move actually depends on
There isn’t a universal answer, and anyone offering one without looking at your file is guessing. The variables that matter: your balance and loan types, whether any loan was disbursed on or after July 1, 2026, whether you’re pursuing PSLF, how many qualifying months you’ve already banked, your income and household size, and whether you’re close enough to a forgiveness threshold that the tax treatment of the discharge becomes part of the math. A few things are worth knowing in general terms. IBR remains available and counts toward PSLF. PAYE and ICR are still available to borrowers with older loans but end no later than July 1, 2028, which makes them a bridge rather than a destination. The Repayment Assistance Plan counts toward PSLF and carries a useful interest benefit, but runs 30 years to its own forgiveness and closes off the Buyback program. And consolidating in 2026 can pull all of your loans into a narrower set of options permanently — occasionally the right move, never a casual one.Where we are on this
We hold notice dates and transition deadlines for the clients we work with, and we’ve been tracking the second 30-day clock the same way we tracked the first. If a final notice has landed on a file we handle and a decision needs making, that’s a direct call with a recommendation attached — not a mass reminder that a deadline exists somewhere. If you’ve received one of these letters and you’re not sure what it means for you specifically, that’s the question your own file answers and an article can’t.This article is general information, not legal or financial advice for your particular situation. Federal student loan policy is moving quickly; the details here are accurate as of October 21, 2026. The Student Loan Help Group is a private company and is not affiliated with the U.S. Department of Education. Help with federal student loans is available free of charge at studentaid.gov.
Recent Posts
tslhg-admin
You Missed the SAVE Deadline
tslhg-admin