Student Loan Autopay Interest Reduction: Deadline Now Dec 31

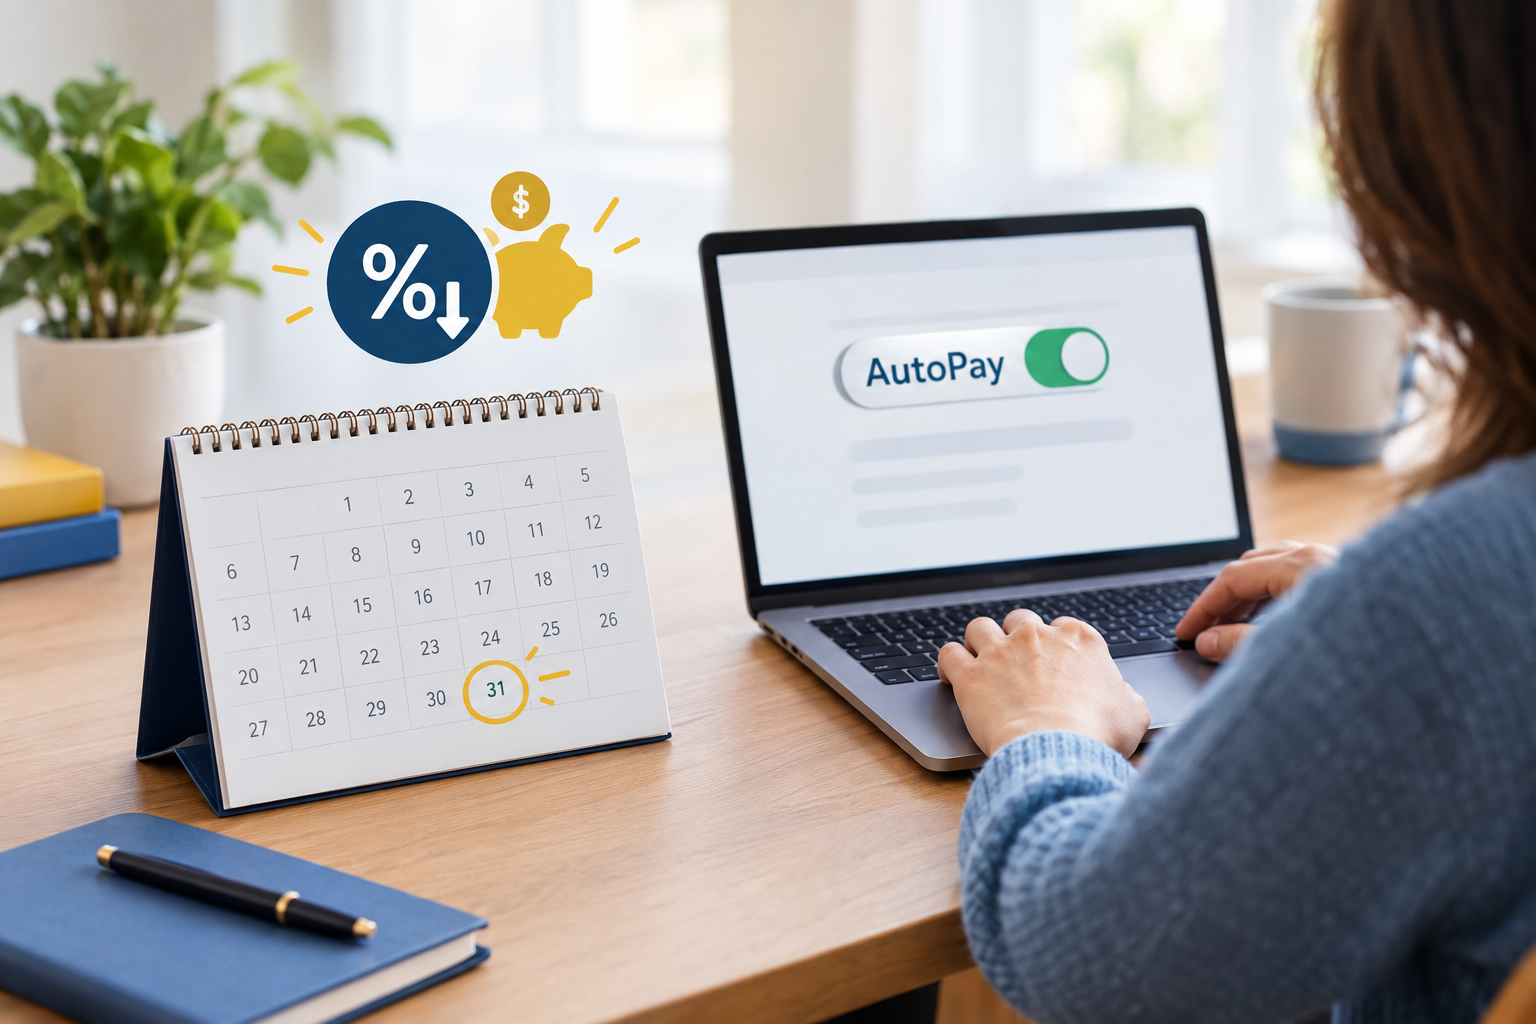
Good news if you missed the September 30 deadline: You still have time to sign up for the temporary 1% student loan interest rate reduction. The Department of Education has extended the deadline for borrowers to enroll in autopay from September 30 to December 31, 2026. Borrowers who enroll by the new deadline, as well as those who were already enrolled, can receive the reduced interest rate through June 30, 2028, as long as they remain enrolled and continue to meet the program's requirements. Here's what the extension means for borrowers who are making payments now, including teachers, nurses, government employees and others working toward PSLF.
What Changed?

The Department originally announced the temporary interest rate reduction in June 2026. Under the program, eligible borrowers enrolled in autopay receive a 1 percentage-point interest rate reduction, compared with the previous 0.25% reduction, through June 30, 2028. The original enrollment deadline was September 30. That deadline has now been pushed back three months. The new deadline is December 31, 2026. According to the Department, nearly 2 million federal student loan borrowers had enrolled in autopay by the time of the extension. Already enrolled in autopay? You should not need to enroll again. The Department says borrowers who were already enrolled when the program was announced had their interest rate automatically adjusted to the 1% reduction. The Department's original announcement has additional details about which loans are eligible and how the reduction works.

What Does This Mean for Teachers, Nurses and Public Servants?

For borrowers working toward Public Service Loan Forgiveness, the extension gives you another three months to set up autopay and take advantage of the temporary interest rate reduction. There's another reason PSLF borrowers should take payment timing seriously. Under current PSLF rules, qualifying payments must be made on time, and the former 15-day grace period is no longer available. That means a borrower who is counting on every month of qualifying employment needs to make sure each required payment reaches the servicer by the due date.  Autopay can help with that. For a teacher juggling the start of a school year, a nurse working overnight shifts, or a government employee with a busy schedule, automatic payments can reduce the risk of forgetting a payment and losing a qualifying month. Just remember that autopay does not make a payment automatically qualify for PSLF. Your loan type, repayment plan, qualifying employment, and other PSLF requirements still apply. 

What Should You Do Now?

If you're not enrolled in autopay, log in to your loan servicer's website and look for the automatic payment or autopay setting. Enrolling takes only a few minutes. If you can’t enroll today, put December 31, 2026 on your calendar, and aim to set it up well before then. Already enrolled? Check that your bank account information is still current and that you have enough money available for your scheduled payments. If you're in default, autopay is a later step. Borrowers must first get their eligible loans back into repayment before enrolling. See our guide on how to get out of student loan default in 2026 for more information.

Quick FAQ

What is the new autopay deadline? December 31, 2026. The Department extended the original September 30 deadline by three months. How much is the student loan autopay discount? Eligible borrowers can receive a 1 percentage-point interest rate reduction, compared with the previous 0.25% reduction. The temporary benefit runs through June 30, 2028. Does autopay help with PSLF? It can help you make payments on time, but autopay itself does not determine whether a payment qualifies for PSLF. Already have autopay? The Department says borrowers who were already enrolled when the program began have already received the 1% adjustment. The autopay deadline is now December 31, but your repayment strategy is bigger than this one benefit. If you're unsure whether your current repayment plan still makes sense, schedule a complimentary consultation with TSLHG to review your options.
This article reflects federal student loan guidance available as of September 30, 2026. This information is for educational purposes and is not legal, financial or tax advice.